The Net Worth Method: Proving Unreported Income
I once sat with a client whose bank statements told a story their tax return couldn't explain. Their reported income was modest, but the money in the accounts kept growing, debts kept shrinking, and personal spending never seemed to slow down. That gap is exactly what the net worth method is built to expose. It's one of the core tools I use in forensic accounting services when a paper trail alone doesn't add up, and it pairs closely with our bank deposit analysis method as part of a broader approach to proving unreported income.
What the Net Worth Method Actually Does
At its core, the net worth method compares what someone says they earned to what actually happened with their money. I start by calculating a person's net worth at the beginning of a period, then again at the end. If their net worth increased, that increase has to come from somewhere: wages, business income, loans, gifts, or some other documented source. When the increase is larger than what's reported on their tax returns or in their accounting records, the difference points to income from a source that was never disclosed.
This is the plain-language version I give clients and, when necessary, judges: it's not an accusation, it's a reconciliation. The method doesn't assume wrongdoing. It simply tests whether the numbers make sense and whether the person had access to funds that don't show up anywhere in their financial records. It tends to be most useful when someone's lifestyle, spending habits, or growing pile of assets don't line up with the income they've claimed.
A Real-World Example of Hidden Income
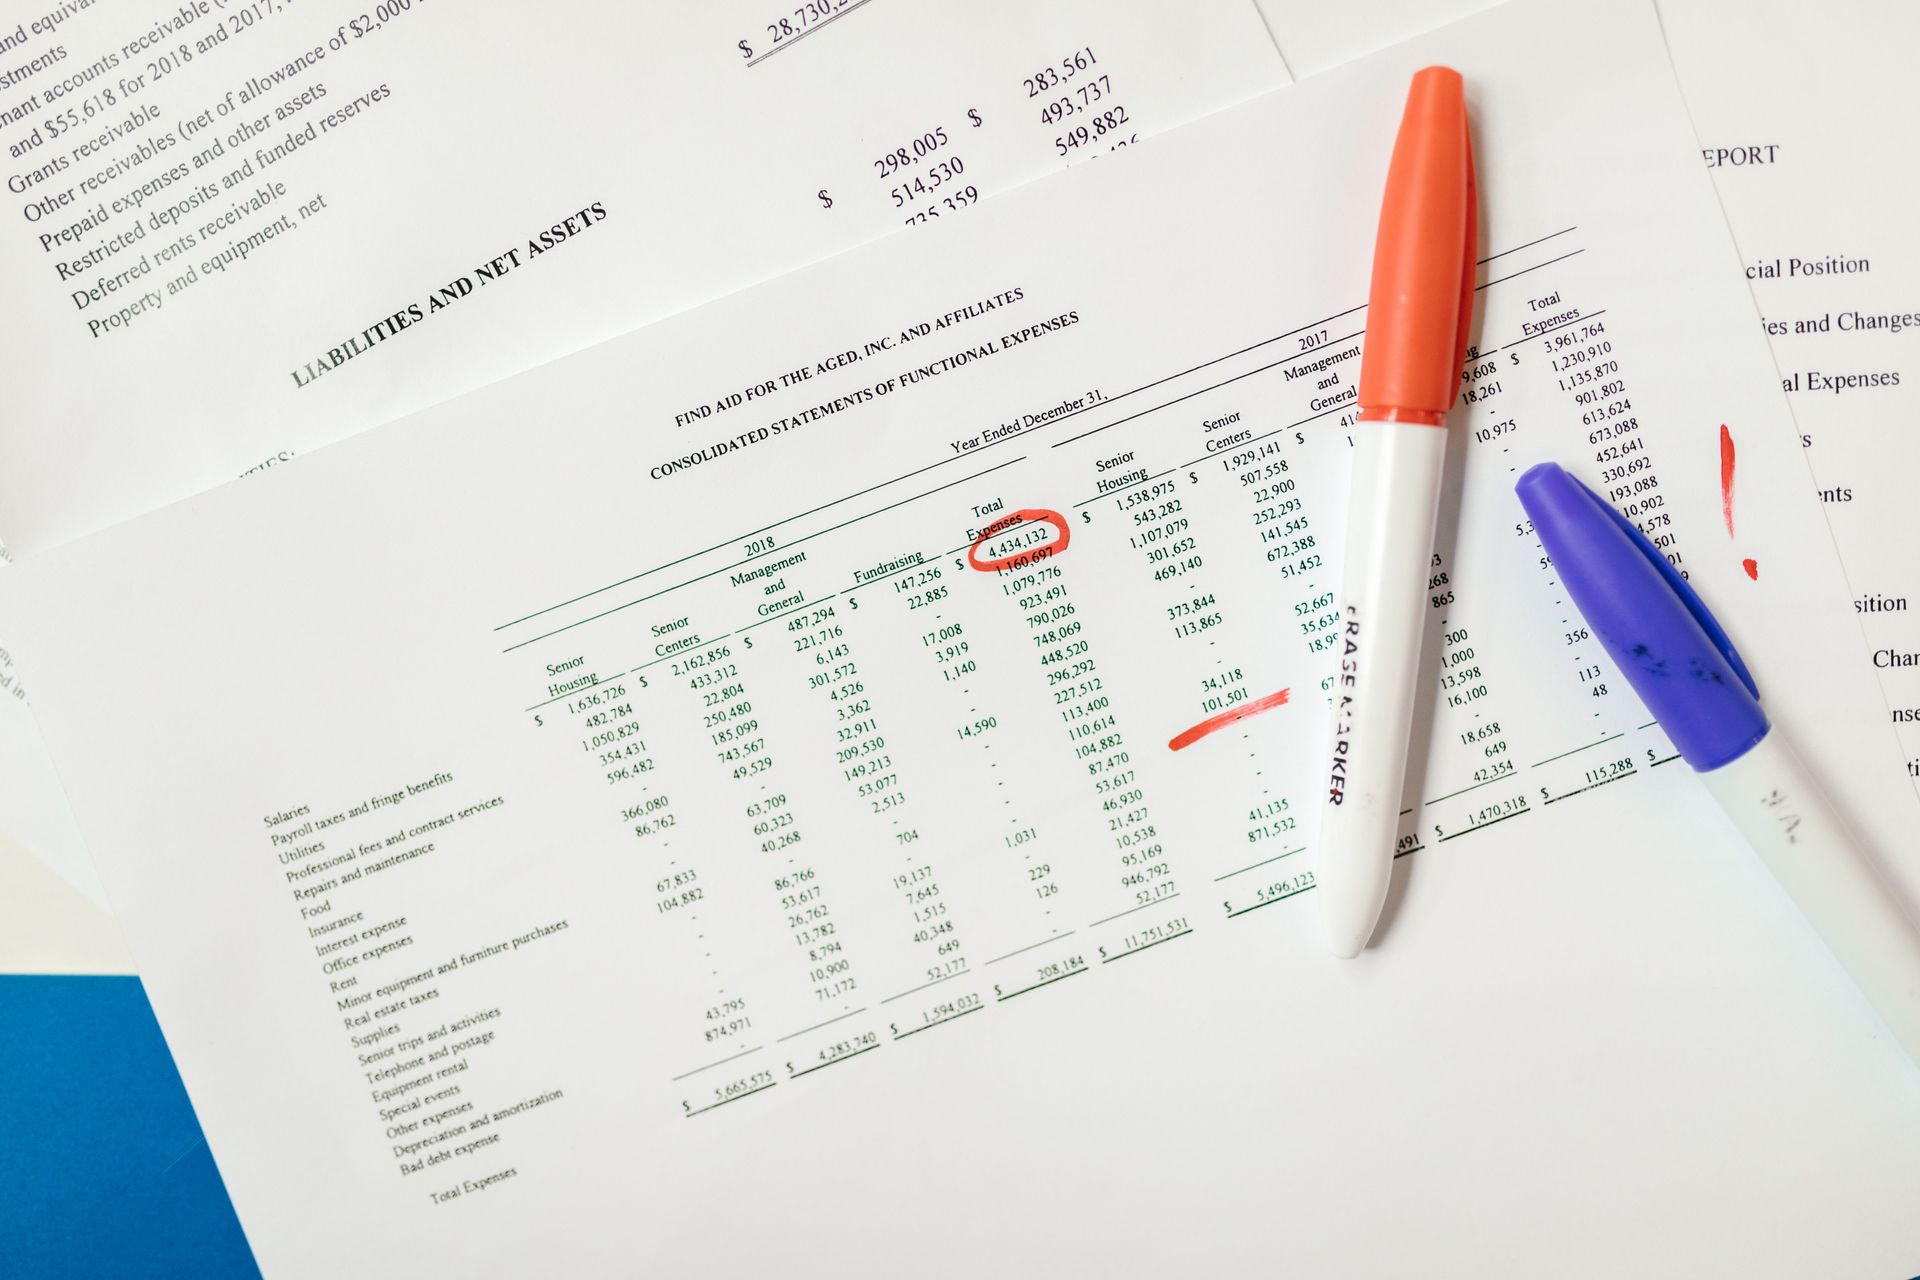
In one matter I worked, an individual's tax returns showed relatively modest earnings, but their bank balances kept climbing, their debts kept shrinking, and their personal spending didn't match what the returns claimed they were bringing home. To get to the bottom of it, I calculated their net worth at the start of the year and again at the end, then compared that change against their stated income. The increase in assets simply couldn't be explained by wages, business income, or any documented loans or gifts on record. That gap showed the individual had access to funds that weren't reported anywhere, and it became a key indicator that additional, unreported income existed outside the records I'd been given. I've written more generally about how forensic accountants track down hidden assets, and this case is a good illustration of that work in practice.
Where the Net Worth Method Gets Complicated
The trickiest part of this work is building an accurate starting point. If the opening net worth is wrong, every calculation that follows is wrong too, so every account, debt, and asset has to be captured completely, with nothing missing and nothing double-counted. It's painstaking, deliberate work, and there's no shortcut around it.
The second challenge is estimating living expenses when records are incomplete. People pay bills in cash, mix personal and business spending across the same accounts, or spread their finances across multiple institutions. In those cases, I have to piece together an accurate picture of someone's actual cost of living from whatever evidence is available, rather than relying on a single, clean data source. The method works well, but it requires careful work at the outset and a realistic understanding of how people actually spend money, not just what their records claim.
The net worth method doesn't accuse anyone of anything. It simply asks whether the numbers add up, and lets the evidence answer that question.
How Opposing Experts Try to Attack It
Because this method carries real weight in litigation, it draws scrutiny, and I expect that. The first line of attack is usually the accuracy of the starting point. Opposing experts will argue that an asset or a debt was missed, or that a balance wasn't captured correctly. I answer that by showing exactly how the opening net worth was built, listing every account, every balance, and the supporting documentation behind each one. A properly documented foundation simply doesn't hold up to that kind of criticism.
The second common attack targets the living-expense estimates. Opposing experts may claim the person actually spent less than the evidence suggests, or that certain expenses shouldn't count at all. I address that by tying every estimate back to real records: bank statements, credit card activity, loan payments, and other documentation, and walking through exactly how each spending category was calculated.
The third argument is that the net worth increase came from loans or gifts rather than unreported income. I address this by checking whether loan documents, actual repayment activity, or a pattern of gifting exist. If there's no evidence to support the claim, the explanation simply doesn't stand up.
When the Net Worth Method Is the Wrong Tool
As much as I rely on this method, it isn't the right tool for every situation, and I think it's important to say that plainly. When good records already exist, and income can be measured directly from reliable documents like complete, consistent bank statements, tax returns, and accounting records, there's no need to estimate income through a net worth analysis. The direct evidence is already there.
It's also the wrong approach when a person's assets and debts simply can't be identified or verified. If key accounts are missing, records are unavailable, or someone's financial life is too fragmented to build an accurate starting point, the method loses its footing before it even begins.
And finally, when the real question is about business performance rather than personal income, direct analysis of business records is a more accurate path than examining someone's personal net worth. Choosing the right method for the right question is just as important as executing the method correctly.
Putting It All Together
The net worth method is one of the most reliable ways to prove unreported income when someone's lifestyle and assets tell a different story than their tax returns do. It takes patience, a rigorous starting point, and a clear-eyed read on how people actually spend and move money, but done right, it holds up under serious scrutiny in fraud, tax, and divorce matters alike.
If you're facing a situation where the numbers on paper don't match what you're seeing in someone's finances, I'd be glad to help you figure out whether the net worth method, bank deposit analysis, or another approach is the right fit. Contact us to talk through your case.